AP automation platforms deliver measurable improvements in invoice processing speed, approval routing, and payment visibility. They reduce manual keying, enforce workflow rules, and produce dashboards that give finance teams real-time line of sight into outstanding liabilities. For companies processing tens of thousands of invoices each month, automation is the only practical way to maintain control at scale.
But automation optimises the approval process. It does not audit the transactions already paid. And that distinction matters, because the largest source of recoverable AP leakage sits in historical payments, not in invoices currently moving through the queue.
What Automation Does and Does Not Check
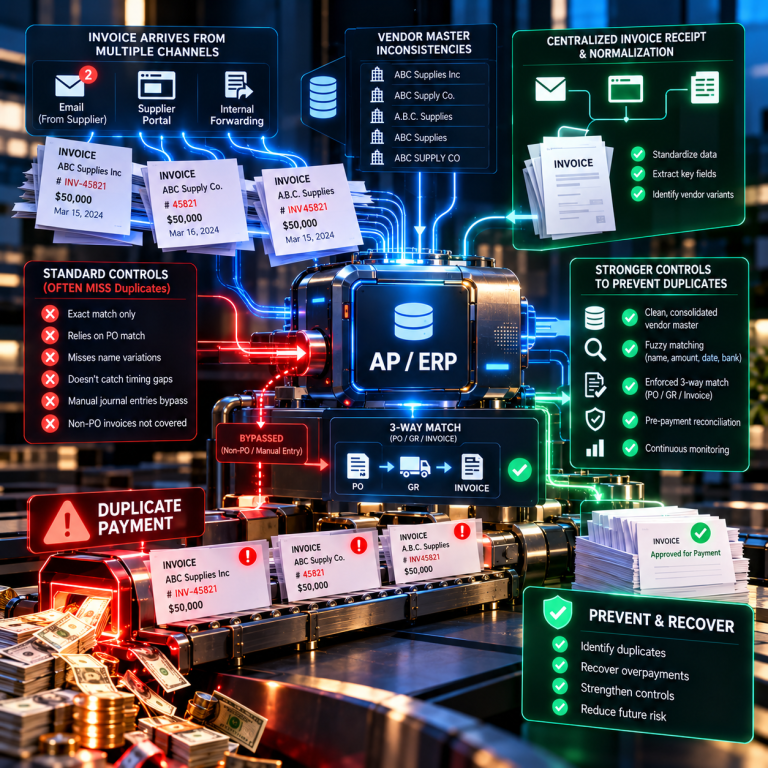
A typical AP automation platform validates that an invoice matches a purchase order, that the amounts fall within tolerance, that the necessary approvals have been obtained, and that the supplier is in the master file. If those conditions are met, the invoice is approved for payment. The system prevents invoices from being paid twice at the same time, and it stops processing when a three-way match fails or an approver rejects a line item.
What the system does not do is verify the commercial accuracy of the charge. It does not confirm that the unit price on the invoice matches the contracted rate. It does not check whether a prompt-payment discount was earned and applied. It does not compare the current invoice to an invoice paid six months ago to detect a duplicate submitted under a different invoice number. It does not validate tax calculations or freight charges. It processes the invoice as presented, assuming the data is correct.
When a supplier billing system generates an invoice with an incorrect rate, the automation platform approves it if the variance is within tolerance. When a regional office pays an invoice manually, then submits it again through the central system, automation flags the second submission only if the invoice number and amount are identical. When a supplier charges sales tax in a jurisdiction where your company is exempt, the payment goes through unless someone manually spots the line item.
The Scope of Hidden Overpayments
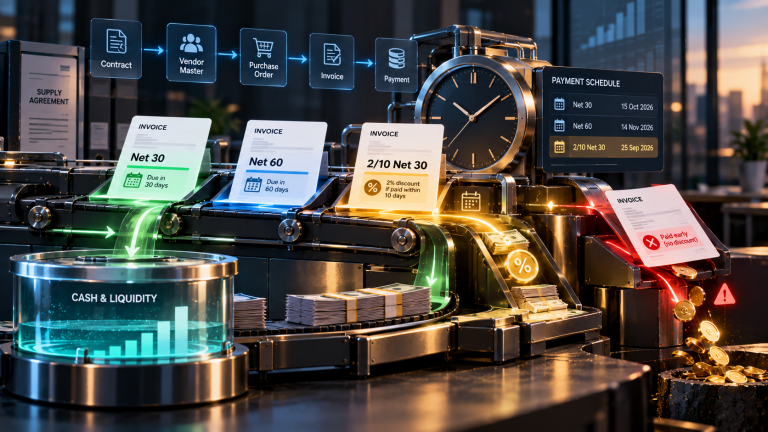
Finance teams running mature AP automation platforms still discover material overpayments during recovery audits. Duplicate invoices represent the most common category, particularly when the same service or shipment is invoiced by multiple entities within a supplier group, or when an invoice is paid before it enters the ERP and then paid again through normal workflow. Early-payment discounts that were earned but not deducted represent another frequent finding, especially in organisations where terms vary by supplier and payment run timing does not align with discount windows.
Pricing errors occur when contract amendments are not updated in the purchase order or when tiered volume pricing is applied incorrectly. Freight and handling charges are routinely overbilled, particularly on international shipments where multiple parties add fees. Tax charges on services delivered in jurisdictions with complex nexus rules produce frequent errors, and many suppliers apply blanket tax rates without checking actual liability.
Automation platforms cannot catch these errors because the validation logic operates at the invoice header and line level, not across the entire payment history. Detecting a duplicate invoice submitted six months later with a different invoice number requires cross-referencing payment dates, amounts, purchase orders, and supplier identifiers across thousands of records. Identifying a pricing error requires comparing each line item to contract schedules, rate cards, and volume tier breakpoints. Validating tax charges requires mapping each transaction to jurisdiction-specific tax rules and exemption certificates.
Why Retrospective Analysis Matters
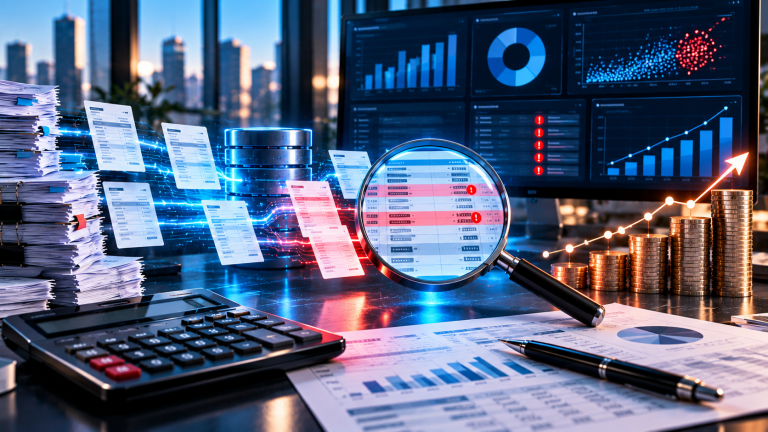
The payments already in your ERP represent the full record of what your company actually paid, not what the approval workflow intended to pay. Automation improves the accuracy of future payments, but it has no mechanism to examine past transactions. A three-year lookback across a high-volume AP environment typically includes millions of line items, thousands of suppliers, and hundreds of contracts. Errors that occur at a rate of less than one percent still produce material recovery opportunities when applied to that volume.
Recovery analysis requires extracting payment data from SAP, Oracle, or JD Edwards, then running transaction-level tests that compare paid amounts to contract terms, prior invoices, tax rules, and standard pricing. The process is forensic, not operational. It does not improve workflow or prevent future errors. It identifies money that left the company incorrectly and is still recoverable from suppliers.
What Finance Teams Should Do
Implement and optimise AP automation for workflow efficiency and control. Separately, conduct periodic recovery audits to identify overpayments in the historical transaction base. The two activities serve different purposes and do not conflict. Automation handles the forward-looking process. Recovery handles the backward-looking analysis.
Most finance teams lack the internal resources to conduct detailed recovery audits while managing daily operations. Specialist recovery firms work on contingency, extracting and analysing payment data, validating findings with suppliers, and handling the recovery process without requiring finance staff time upfront. If your organisation processes significant AP volume and has not conducted a recovery audit in the past three years, the exercise typically pays for itself several times over. Fintralis works exclusively on contingency with companies running SAP, Oracle, and JD Edwards, focusing on organisations with annual AP spend above $50 million where transaction volume makes forensic analysis worthwhile.
Frequently asked questions
Does AP automation prevent duplicate payments?
AP automation reduces future duplicate invoices by flagging exact matches during approval, but it does not identify duplicates already paid in prior periods. Most platforms have no retrospective audit function. Payment exceptions that bypass normal workflow, manual cheques, or invoices paid before the system was implemented remain outside the automation logic and often contain duplicate payments.
What types of overpayments does AP automation miss?
AP automation typically misses pricing discrepancies when the invoice amount differs from the purchase order or contract rate, early-payment discounts that were not taken, incorrect freight or tax calculations, and supplier billing errors where quantities or rates are wrong but the invoice format is valid. The software approves the invoice if it matches basic rules, even when the underlying charge is incorrect.
How much do companies typically recover from historical AP audits?
Recovery amounts vary widely based on company size, industry, and payment volume. Many organisations recover between 0.2% and 1.5% of their three-year audited AP spend. The actual figure depends on control maturity, supplier complexity, and whether the company has conducted any previous recovery work. High-transaction-volume environments with many suppliers and contract amendments tend to yield higher recovery rates.
Can we audit for overpayments while using AP automation software?
Yes. AP automation handles forward-looking workflow, while recovery audits analyse historical paid transactions across the ERP system of record. The two processes are independent. Recovery firms extract payment data directly from SAP, Oracle, or JD Edwards, then apply detailed transaction-level tests that automation platforms do not perform. There is no conflict or system overlap.
Why don’t ERP systems catch these overpayment errors automatically?
ERP systems execute the payment process as instructed but do not verify the commercial accuracy of each line item. They check that an invoice has the required approvals and matches a purchase order within tolerance, but they do not validate contract pricing, confirm that early-payment terms were applied, or detect duplicate invoices paid weeks apart under different invoice numbers. Those checks require cross-referencing thousands of transactions against contracts, prior payments, and supplier rate cards.
Who is responsible for recovering overpayments after they happen?
Responsibility varies by organisation. Some finance teams assign recovery projects to internal audit or accounts payable staff, while others engage specialist recovery firms on contingency. The key constraint is resource availability and expertise in forensic transaction analysis. Recovery requires extracting and analysing millions of line items, which is impractical for most finance teams to handle alongside daily operations.